Potentially taxable onchain crypto activity will reach at least $457 billion worldwide in 2025, while international reporting rules may only capture a fraction of that, according to a new chainanalysis. Report.
The United States accounted for an estimated $112.6 billion of the total, while North America led all regions with $134.6 billion, followed by the European Union at $125.1 billion.
Estimates include realized profits, income from activities such as mining, staking and lending, and crypto-structured payments across the six major blockchains, but exclude trading and other activities conducted within centralized exchanges.
Chainanalysis said transactions covered by the Organization for Economic Co-operation and Development’s (OECD) Crypto-Asset Reporting Framework (CARF) accounted for only 14% of the onchain taxable activity it identified. The remaining 86% includes decentralized exchanges, peer-to-peer transfers, onchain revenue streams and payment activities.
CARF, developed by the OECD in 2022, requires covered crypto service providers to report customer transaction data to tax authorities.
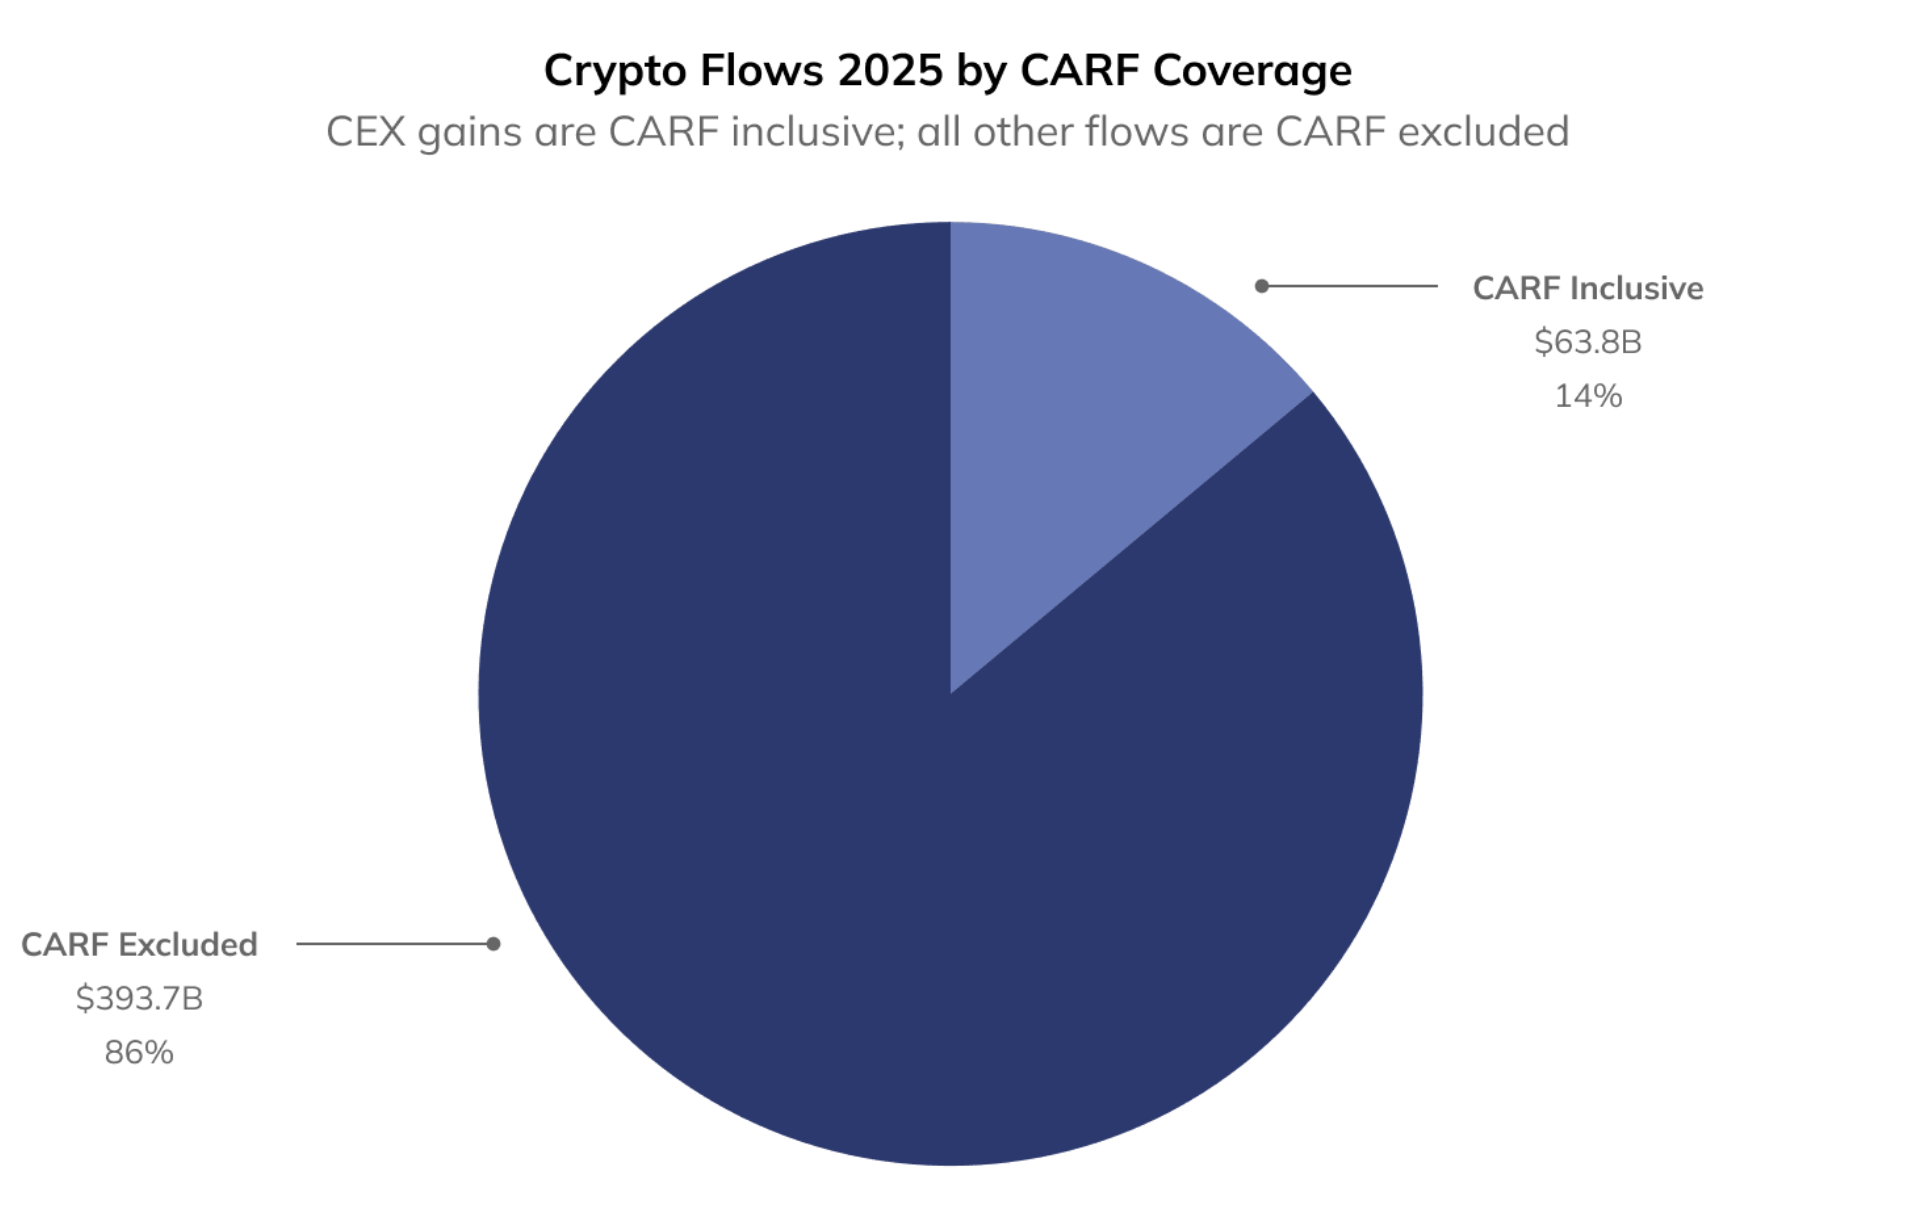
CARF covers only 14% of potentially taxable onchain crypto activity.
Source: Chainanalysis
Related: Chainlysis sues TRM Labs over $95 million ICE contract
CARF’s limits on onchain tax reporting
CARF data collection began on January 1, 2026, in 48 jurisdictions, including the United Kingdom and the European Union, requiring Cover Crypto platforms to collect additional customer and tax residency information.
Under CARF, in-scope crypto providers collect customer and tax residency information and report transaction data to domestic tax authorities, which can then share that information across borders.
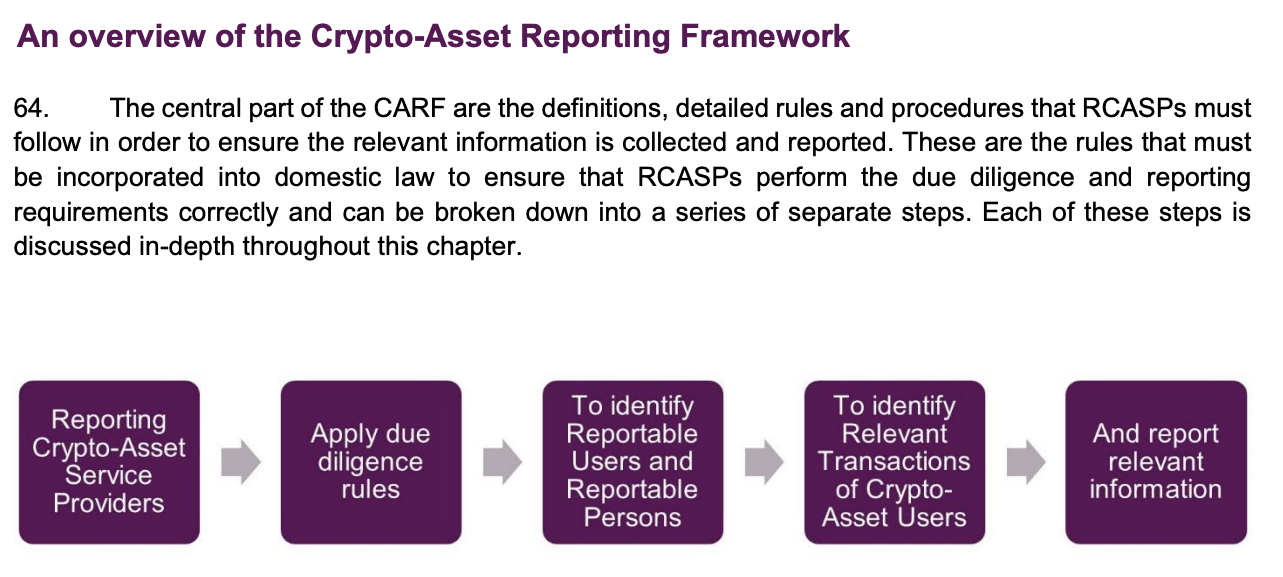
CARF Framework. Source: OECD
CARF’s focus on crypto intermediaries also helps explain the gaps highlighted by the chainanalysis. Colby Mangels, a former OECD advisor who worked on CARF, told Cointelegraph in January that the framework was designed around intermediaries that facilitate crypto transactions as businesses.
Most decentralized finance therefore remains outside the scope of reporting, as there may be no centralized operator or custodial relationship to impose reporting requirements.
This may change as regulators develop rules for decentralized platforms. Mangels said tax authorities are looking at developments in anti-money laundering regulations, including efforts to determine when DeFi platforms or their operators should be considered regulated crypto service providers.
magazine: The SEC’s proposed crypto rules likely won’t spark a new ICO boom