The strategy’s bitcoin treasury may be less vulnerable to a crypto market crash than a prolonged loss of capital-market access, a risk that could threaten its ability to fund its roughly $1.76 billion in annual obligations without selling bitcoin, according to a recent analysis by Regime Intelligence.
According to ReportStrategy’s 840,447 BTC stash sits behind about $22 billion in debt and preferred claims, meaning the company’s bitcoin accumulation model relies on its ability to continually raise new capital to meet obligations.
Contrary to popular belief, the strategy’s (MSTR) biggest weakness is not bitcoin-driven price declines or liquidity events, but its continued reliance on access to capital markets. The report notes that Strategy’s loan does not work like a conventional bitcoin-backed margin loan, with no BTC-linked margin calls that would force the company to divest its holdings as prices fall.
Regime Intelligence’s stress test showed that bitcoin would need to depreciate by roughly 96% before the strategy’s bitcoin holdings and reserves no longer cover the convertible notes. However, this shifts risk to the other side of the balance sheet, as the strategy must continue to pay out approximately $1.76 billion in annual preferred dividends and interest regardless of bitcoin’s price.
“In my opinion, MSTR’s main challenge is to keep the flywheel operational to cover annual debt and discretionary charges,” the report’s author, Sherif Saad, told Cointelegraph.
He said investors should look at the strategy’s preferred share price and cash reserves, which currently cover about 2.6 times its annual charges.
If funding conditions deteriorate, its bitcoin collection strategy may reverse, forcing a greater reliance on reserves and bitcoin sales to meet its obligations.
“During a prolonged BTC decline, the problem becomes more serious if MSTR’s share price and mNAV decline at the same time,” he said, adding that raising capital would then become “progressively more difficult or expensive.”
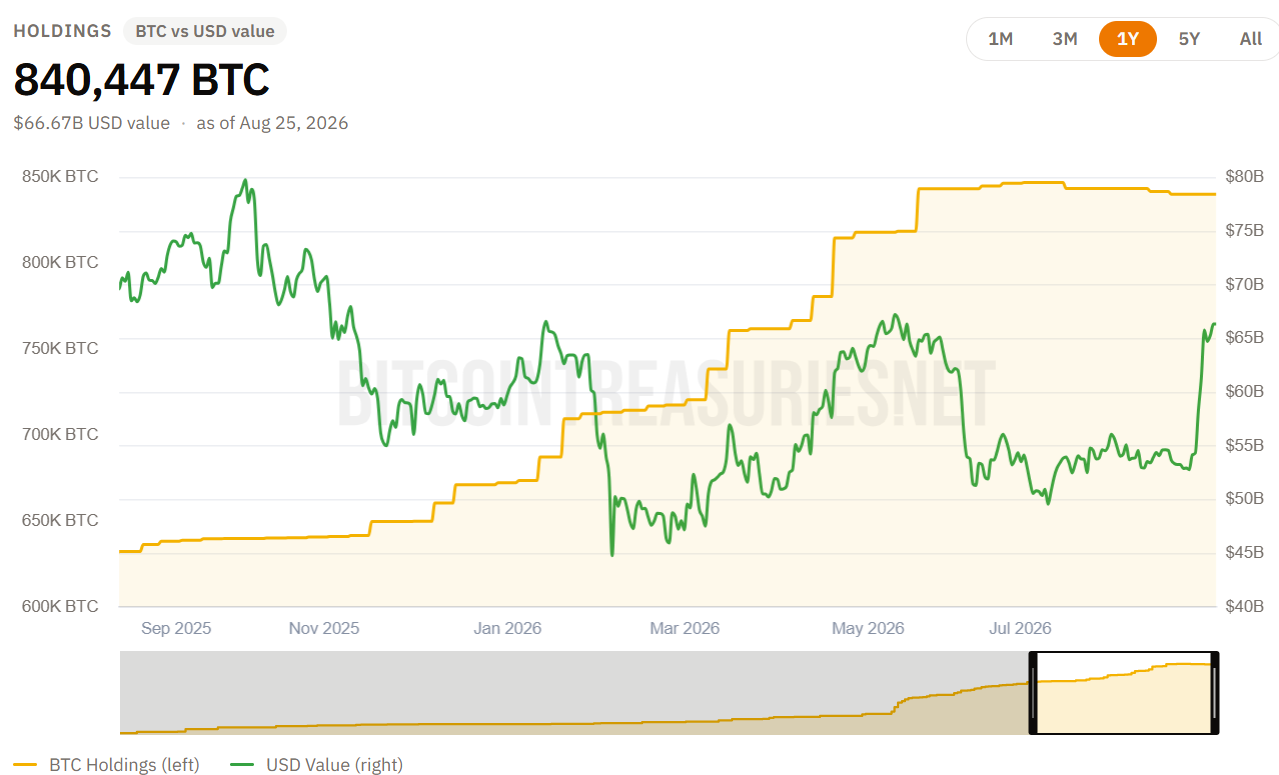
After Bitcoin’s recent recovery, Strategy’s BTC stash is now worth $66.7 billion, based on the company’s spending of $63.36 billion. Source: BitcoinTreasuries.NET
Related: US Treasury doubles long-term buybacks as Standard Chartered analysts see $100K BTC
Michael Sayler’s juggling act
Much of the perceived risk around the strategy centers on its willingness to tap bitcoin onto its balance sheet, especially after executive chairman Michael Saylor spent years promoting a “never sell” approach. So, it came as a surprise to some bitcoiners when the strategy started selling BTC this year to meet its other business obligations.
The company has sold bitcoin four times since May, including a recent sale of 1,690 BTC, with proceeds from the latest sale used to pay preferred stock dividends, share repurchases and its growing US dollar reserves.
Despite the sell-off, Strategy CEO Fong Le reminded investors that the company has accumulated “about 25 times more” bitcoin than it has sold this year. He told CNBC earlier this month that the company plans to resume buying bitcoin later this year.
Related: Crypto Biz: Bitcoin’s $116M Self-Custody Wake-up Call